One of the most consequential infrastructure projects in Southeast Asian finance is being built with almost no public attention. Project Nexus, an initiative of the Bank for International Settlements, is connecting the domestic instant payment systems of Malaysia, Singapore, Thailand, Indonesia and the Philippines into a single interoperable network. When it is fully live, moving money between these countries could work much like moving it within one.
What Nexus is trying to solve
Each ASEAN country has built an excellent domestic instant payment rail. Thailand has PromptPay, Singapore has PayNow, Indonesia has BI-FAST, Malaysia has DuitNow. Domestically these are fast, cheap and near universal. Crossing a border, however, has traditionally meant falling back on correspondent banking, with its delays, fees and pre-funded accounts.
Nexus addresses this by standardising the connection rather than building bilateral links one pair at a time. Instead of every country negotiating a separate arrangement with every other country, each connects once to a common framework.
It is already happening bilaterally
Even before Nexus completes, cross-border QR is spreading fast. According to Nation Thailand, Thailand's PromptPay system already connects through cross-border QR links with Singapore, Vietnam, Indonesia, Laos, Japan and Hong Kong.
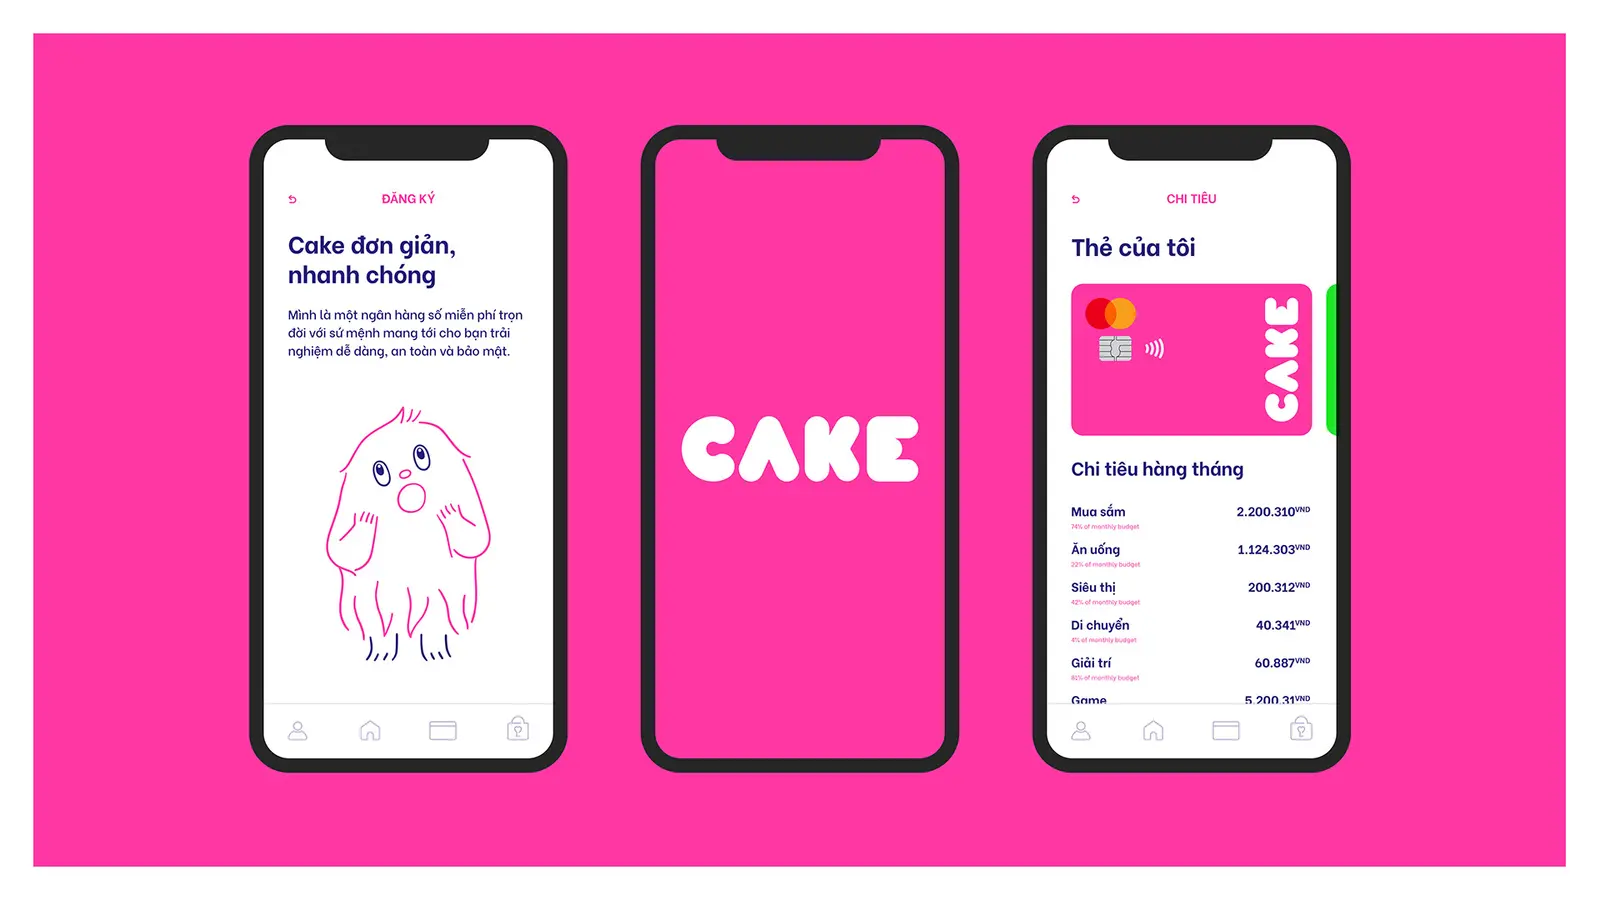
The consumer experience is already tangible. Cake by VPBank, one of Vietnam's leading digital banks, launched a feature in 2026 letting Vietnamese users pay directly from their domestic dong accounts in Thailand, Laos and Cambodia, without opening a foreign currency account or carrying cash.
Why the scale matters
The volumes involved are substantial. According to the Chambers and Partners Fintech 2026 Thailand guide, PromptPay and Thai QR account for approximately 44 percent of account-to-account electronic payments in Thailand. Across the region, digital payment transactions are projected to exceed 1.5 trillion dollars in 2026 according to the Money20/20 Future of Fintech in APAC report.
Connecting rails of that scale changes the economics of regional commerce. A Thai small business selling to Malaysian customers, a Filipino worker sending money home from Singapore, an Indonesian tourist paying in Bangkok, all currently pay a friction tax that Nexus is designed to remove.
Each country already has a fast, cheap domestic rail. Nexus is about making the border stop being the expensive part.
How Nexus works
Project Nexus began at the Bank for International Settlements Innovation Hub as a design for connecting domestic instant payment systems through a single standard gateway. Instead of each pair of countries building a separate link, each country connects its system to Nexus once and can then reach every other connected country. Nexus handles the technical translation between systems, while foreign exchange providers quote rates for conversion between currencies, and sanctions screening is carried out within the process. The aim is to make cross-border payments as fast and simple as domestic ones, typically completing within seconds.
Who is building it
After the BIS completed the design and testing phases, the central banks of Malaysia, the Philippines, Singapore and Thailand, together with the Reserve Bank of India, formed an organisation to build and operate Nexus. Other central banks have taken part as observers. Connecting India's Unified Payments Interface, one of the world's largest instant payment systems, alongside Southeast Asian systems would create a very large network for remittances and trade.
The bilateral links that came first
Before Nexus, Southeast Asian central banks built links one pair at a time. Singapore's PayNow and Thailand's PromptPay were linked in 2021, the first real-time retail payment link of its kind between two countries in the region. Other links followed for QR payments and transfers between Malaysia, Indonesia, Thailand, Singapore, the Philippines and Vietnam. These links proved the demand and the technology, but every new pair needed its own negotiations, rules and technical work, which is the problem Nexus is designed to solve.
Foreign exchange in an instant payment
Every cross-border payment involves converting one currency into another. In Nexus, foreign exchange providers compete to quote rates, and the sender sees the rate and fees before confirming. Transparent pricing is one of the main benefits for users, because traditional cross-border payments often hide costs in the exchange rate. Competition among providers should narrow the margins charged on popular routes.
What it means for consumers and small businesses
For a worker in Singapore sending money to the Philippines, or a small business in Thailand selling to customers in Malaysia, connected instant payments mean money arriving in seconds, at known cost, using the same apps and identifiers they use at home, such as a phone number. For merchants, it means accepting payments from tourists and online customers in neighbouring countries without card fees.
What it means for banks and fintechs
Banks and remittance companies that earned margins from slow, opaque cross-border payments will face pressure as instant links spread. The opportunities move to services built on top of the rails: foreign exchange provision, merchant tools, compliance and fraud prevention, and products that combine payments with credit or savings. Firms that connect early and design around the new rails will be better placed than those that defend old margins.
Challenges ahead
- Each country has its own rules on data, anti-money laundering checks and capital flows that must be respected.
- Fraud can move faster on instant rails, so strong controls are essential.
- Liquidity in less common currency pairs may be thin at first.
- Governance among several central banks takes time to agree.
The competitive implication for banks and fintechs
Cross-border remittance and payment margins have historically been protected by complexity. When a regional network makes transfers instant and cheap at the infrastructure layer, that protection erodes. Providers whose value rested on navigating the complexity will need a different proposition.
The opportunity is equally real. Any business selling across ASEAN gains a materially simpler payment environment, and any fintech building services on top of connected rails inherits reach it could never have built alone.
What brands should do now
The practical move is to understand which rails matter in each target market and design for them. In Thailand, PromptPay support is effectively mandatory. Across the region, wallets including TrueMoney and Rabbit LINE Pay carry substantial share. As Nexus links these systems, brands already integrated locally will find regional reach arrives largely for free.
This is exactly where SpinDepth helps, positioning financial brands credibly as Southeast Asia's payment infrastructure knits together.
FAQs
Q1: What is Project Nexus?
A1: A Bank for International Settlements initiative connecting domestic instant payment systems across Malaysia, Singapore, Thailand, Indonesia and the Philippines into an interoperable network.
Q2: Is cross-border QR already available?
A2: Yes, bilaterally. Thailand's PromptPay connects with Singapore, Vietnam, Indonesia, Laos, Japan and Hong Kong, according to Nation Thailand.
Q3: How large are these payment systems?
A3: PromptPay and Thai QR account for roughly 44 percent of account-to-account electronic payments in Thailand, and regional digital payments are projected above 1.5 trillion dollars in 2026.
Q4: Who benefits most?
A4: Consumers, small businesses trading regionally, and fintechs building on connected rails. Providers whose margins depend on cross-border complexity face pressure.
For brands entering the region, connected payment rails mean regional reach is becoming default, and that is exactly where SpinDepth helps brands show up.
Source:
Source 1: Bank for International Settlements, Project Nexus
Source 2: Nation Thailand, Thailand's Digital Payment Revolution
Source 3: Chambers and Partners, Fintech 2026 Thailand
Source 4: Fintech News Singapore, PromptPay as a Blueprint to Modernize Trade Finance
You've finished this story
Read on, send it to someone, or ask about it.