In Thailand, people say let me PromptPay you the way people elsewhere say let me send you the money. A national payment system has become a verb. That linguistic detail captures something a statistic cannot: PromptPay did not just get adopted, it became the default assumption about how money moves.
The scale
According to the Chambers and Partners Fintech 2026 Thailand guide, PromptPay and the Thai QR Code payment rail account for approximately 44 percent of account-to-account electronic payments in the country, and the same guide notes PromptPay accounted for roughly 44 percent of e-commerce transaction value in 2025.
Data shared at Money20/20 Asia 2026 and reported by Fintech News Singapore put Thailand at 181.8 million digital banking accounts in January 2026, with transaction volume up 10.6 percent year on year to 3.5 billion. In a country of roughly 70 million people, that account figure tells you how deeply digital payment has penetrated daily life.
Why it worked when others did not
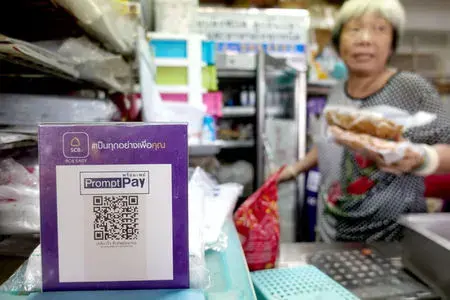
Plenty of countries have launched national payment schemes that never achieved this depth. Several factors distinguish the Thai case. The Bank of Thailand drove it as national infrastructure rather than leaving it to competing private systems, so there was one rail rather than five incompatible ones. It was built free or near-free for consumers, removing the cost objection entirely. And it reached the smallest merchants, from street food stalls to market vendors, where a printed QR code costs nothing to deploy.
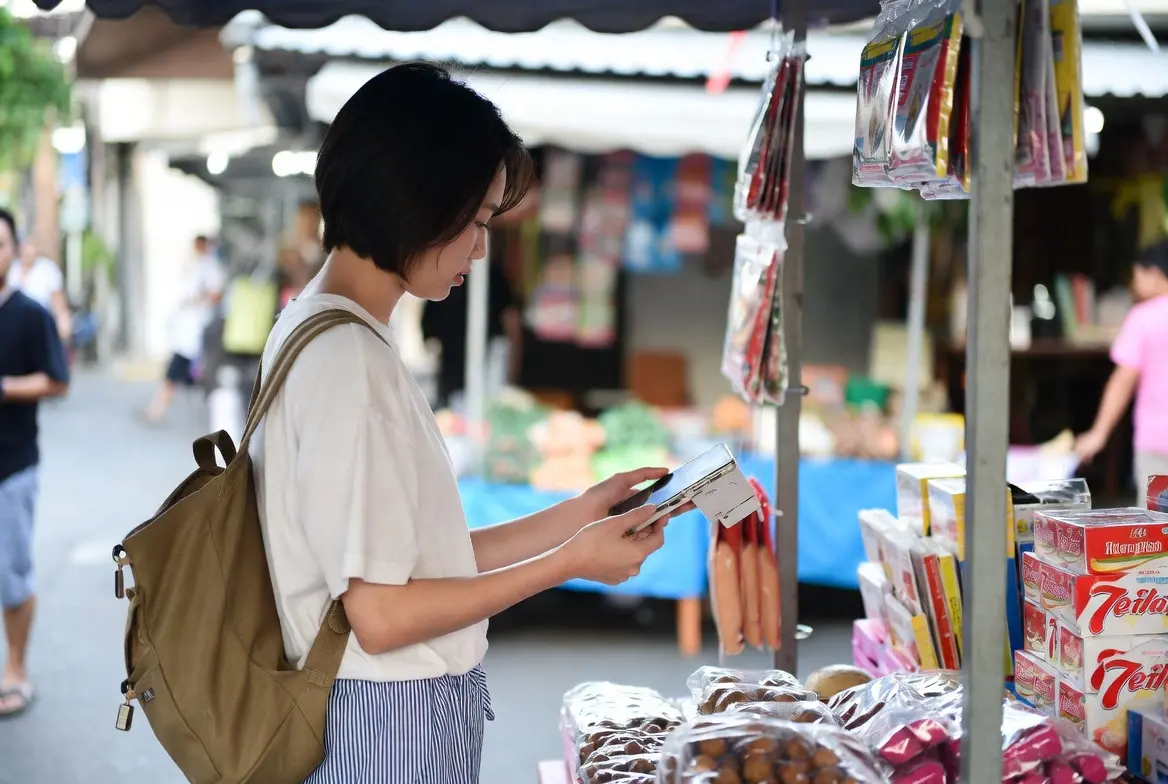
That last point is the hardest part and the most important. A payment system that only works in shopping malls does not become a verb. One that works at a noodle stall does.
From domestic rail to regional model
PromptPay's next chapter is crossing borders. According to Nation Thailand, it already connects through cross-border QR links with Singapore, Vietnam, Indonesia, Laos, Japan and Hong Kong. Thailand has also deepened bilateral QR arrangements with major Chinese payment platforms, creating connectivity with the world's largest digital payments market.
Beyond consumer payments, the model is being studied for trade finance. Fintech News Singapore examined PromptPay as a blueprint for modernising trade finance and infrastructure, on the logic that if a country can build instant, low-cost, universally adopted rails for retail payments, the same architectural thinking can be applied to slower, costlier commercial flows.
A payment system that only works in shopping malls never becomes a verb. One that works at a noodle stall does.
How PromptPay started
PromptPay launched in 2017 as part of Thailand's National e-Payment plan, developed by the Bank of Thailand together with the country's banks and the national payment switch, National ITMX. It lets people link their bank accounts to a mobile phone number or national ID number, so that money can be sent using those identifiers instead of account numbers. Transfers arrive in seconds, at any time of day. A national QR code standard followed, allowing shops and street vendors to accept payments by displaying a QR code, with no card terminal needed.
Why free and simple mattered
A key decision was making small transfers free for consumers, which removed the main reason to keep using cash for everyday payments. Using phone numbers and ID numbers made the system easy to understand. The government's use of PromptPay to pay welfare benefits and relief payments brought in millions of people who might otherwise have stayed with cash. Together, these choices created the network effect that turned PromptPay into a habit.
Cross-border links
Thailand has linked PromptPay with payment systems in several neighbouring countries. In 2021 it connected with Singapore's PayNow, one of the world's first links between two national real-time payment systems, allowing transfers between the countries using phone numbers. QR payment links followed with countries including Malaysia, Indonesia, Cambodia, Laos and Vietnam, so travellers can pay merchants by scanning local QR codes from their home banking apps. These bilateral links are a step towards wider regional connections through initiatives such as Project Nexus.
Lessons other countries draw
Countries studying PromptPay usually focus on a few lessons: strong central bank leadership, cooperation among banks on shared infrastructure, simple identifiers, low or zero fees for consumers, a national QR standard for merchants and government payments to drive early adoption. The hardest part to copy is the last mile: getting small vendors and rural users to adopt the system. Thailand's success there came from making acceptance cheap and simple for the smallest merchants.
Risks that come with instant payments
Instant, free transfers are also attractive to fraudsters, because stolen money can move through several accounts in minutes. Thailand has responded with measures to freeze suspicious accounts quickly, share information about mule accounts and hold banks and telecom firms more responsible for preventing scams. Users can protect themselves by never transferring money in response to unexpected calls or messages and by checking the recipient's name shown before confirming a transfer.
What it means for businesses entering Thailand
Any business serving Thai consumers needs to accept PromptPay and Thai QR payments, whether online or in person. Payment providers offer integrations for websites and apps. Businesses should also plan for cross-border QR payments from tourists and for customers who expect refunds and payouts to arrive as quickly as payments.
What comes next
Thailand is now building on top of this foundation. The Bank of Thailand has said its baht stablecoin guideline has entered its final stage, with regulations expected by 2026 or early 2027, adding programmability to a payment environment that is already instant. The country's first virtual bank, Clicx, began serving the public in June 2026, and TouristDigiPay lets foreign visitors convert crypto to baht through licensed operators and spend it via regulated e-wallets.
Each of these builds on the assumption that instant digital payment is normal, which PromptPay established.
What this means for financial brands
For any brand entering Thailand, PromptPay support is not a feature decision. It is table stakes. A financial product that cannot connect to the rail Thai consumers use by reflex will struggle regardless of how good the rest of it is. Beyond integration, the deeper lesson is about expectation: Thai users expect instant, free, mobile-first money movement, and anything slower or more expensive feels broken.
This is exactly where SpinDepth helps, building products, positioning and presence that fit how Thai consumers actually behave.
FAQs
Q1: How large is PromptPay?
A1: PromptPay and Thai QR account for roughly 44 percent of account-to-account electronic payments and a similar share of e-commerce transaction value in 2025, according to Chambers and Partners.
Q2: Why did it succeed?
A2: Central bank leadership creating one national rail, near-zero consumer cost, and adoption down to the smallest merchants through low-cost QR.
Q3: Where does PromptPay connect internationally?
A3: Cross-border QR links with Singapore, Vietnam, Indonesia, Laos, Japan and Hong Kong, according to Nation Thailand.
Q4: What is built on top of it?
A4: Thailand's virtual banks, a planned baht stablecoin framework, and the TouristDigiPay sandbox for tourists spending converted crypto as baht.
For brands entering Thailand, PromptPay integration is table stakes, and that is exactly where SpinDepth helps brands show up.
Source:
Source 1: Fintech News Singapore, PromptPay as a Blueprint to Modernize Trade Finance and Infrastructure
Source 2: Chambers and Partners, Fintech 2026 Thailand
Source 3: Nation Thailand, Thailand's Digital Payment Revolution
Source 4: Baker McKenzie, Thailand Bridging Payments and Digital Assets
You've finished this story
Read on, send it to someone, or ask about it.