Corporate treasurers in Southeast Asia have long lived with a frustrating constraint: money stops moving when banks close. OCBC and Ant International want to change that. The two companies have launched a tokenised deposit solution for corporate treasury management and liquidity transfers between Singapore and Malaysia, moving Singapore dollar and US dollar liquidity across borders, including outside traditional banking hours, according to Fintech News Singapore on 7 October.
The service runs on Ant International's WhaleRTP platform, known as Whale, which connects blockchain-based assets from multiple financial institutions. It is a concrete example of tokenisation moving from pilot to production in one of the world's busiest cross-border corridors, and it shows why many banks see tokenised deposits, rather than stablecoins, as the right tool for corporate money.
How tokenised deposits work
A tokenised deposit is a digital representation of a commercial bank deposit, recorded on a distributed ledger. Unlike a stablecoin, which is issued by a separate company backed by reserves, a tokenised deposit is a claim on the bank itself, sitting inside the regulated banking system with all the protections and supervision that come with it.
In the OCBC service, a company can move liquidity held in Singapore dollars or US dollars between entities in Singapore and Malaysia continuously. Because transfers are recorded on a blockchain rather than processed in batches, they are not limited by settlement cut-off times or banking hours. The ledger also creates a tamper-resistant transaction history, which reduces the manual reconciliation that treasury teams normally perform.
The design addresses a specific pain point. Groups with entities in several countries need to move cash between them to fund payments, meet local obligations and invest surplus balances. Traditional cross-border transfers depend on correspondent banking, batch processing and cut-off times, which can leave cash stuck over weekends or holidays.
- Partners: OCBC and Ant International.
- Platform: Ant International's WhaleRTP (Whale).
- Currencies: Singapore dollar and US dollar.
- Corridor: Singapore and Malaysia.
- Benefit: continuous transfers outside banking hours and reduced manual reconciliation.
The approach also changes how banks compete for corporate business. A bank that can move a client's money between countries at any hour, with a clean audit trail, offers something that traditional correspondent banking cannot. That makes tokenised deposits a relationship tool as much as a technology project, helping banks keep large corporate accounts as fintechs and payment platforms court the same clients.
What OCBC and Ant say
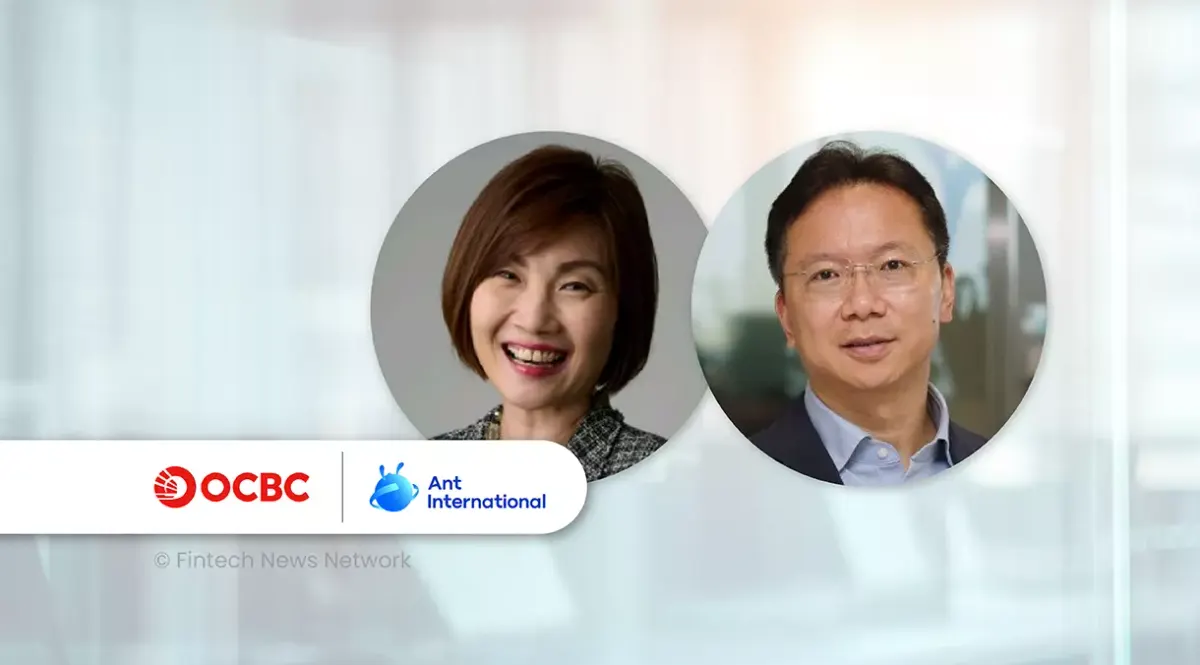
Carmen Chan, deputy head of global transaction banking at OCBC, said tokenisation is moving past experimentation and can deliver practical value for working capital management at scale. She said combining OCBC's blockchain and transaction banking capabilities with the Whale platform helps businesses manage liquidity with greater speed, visibility and efficiency.
Kelvin Li, general manager of platform tech and senior vice president at Ant International, said the Whale platform supports more efficient cross-border treasury across Ant's ecosystem. Ant International, the Singapore-headquartered business that grew out of Ant Group, operates payment and treasury services across many markets and runs the Alipay+ network.
The announcement did not name the corporate client using the service. That is common for treasury products, where companies rarely disclose their banking arrangements, but it means the scale of initial use is unclear.
Stablecoins promise money that moves at internet speed. Tokenised deposits deliver it without leaving the regulated banking system.
Ant International's role is worth noting. Rather than issuing its own money, Ant provides the platform that connects bank-issued tokens, positioning itself as infrastructure for banks rather than a competitor to them. That model lets it work with several banks at once and earn from the network effects of connecting them.
OCBC's tokenisation track record
The launch builds on a series of OCBC projects in 2026. In April, OCBC and its asset management arm, Lion Global Investors, launched a tokenised physical gold fund on a public blockchain. In September, OCBC completed a cross-border US dollar tokenised deposit transaction on Swift's ledger with Citibank, and joined two other Singapore banks in domestic Singapore dollar tokenised deposit transactions on the same ledger.
That sequence shows a bank working across several types of infrastructure: public blockchains for fund tokens, Swift's shared ledger for interbank transfers, and Ant's Whale platform for corporate treasury. Rather than betting on a single network, OCBC is building capabilities that can connect to wherever its clients' counterparties are.
We covered the Swift ledger's debut in our report on Swift's blockchain ledger at Sibos. Its emergence alongside private platforms like Whale suggests tokenised deposits will travel over multiple rails, with banks choosing the route that suits each use case.
Tokenised deposits versus stablecoins
The OCBC launch sharpens a debate running through global finance. Stablecoins have grown rapidly as a way to move dollars on blockchains, and payment companies from Visa to Stripe are building around them. Banks, meanwhile, argue that tokenised deposits offer the same speed with stronger protections, because they remain bank liabilities subject to capital rules, supervision and, in some cases, deposit insurance.
For corporate treasury, the bank argument is persuasive. Treasurers prioritise safety, regulatory certainty and integration with existing banking relationships. A tokenised deposit at OCBC fits into the company's existing accounts and controls, whereas holding stablecoins introduces new counterparties, accounting questions and policy approvals.
Stablecoins retain advantages elsewhere. They are open to anyone, work across platforms and blockchains, and suit consumer payments and crypto markets. The likely outcome is coexistence: tokenised deposits for regulated corporate flows, stablecoins for open networks, and bridges between them. Our report on banks building a stablecoin consortium shows how some banks are trying to have both.
Why the Singapore and Malaysia corridor matters
Singapore and Malaysia share one of the busiest economic corridors in Asia. Thousands of companies operate on both sides of the Causeway, with manufacturing in Johor, headquarters in Singapore and supply chains that cross the border daily. Cash management between entities in the two countries is a constant need.
The corridor already benefits from real-time payment links, including the connection between Singapore's PayNow and Malaysia's DuitNow for retail payments. Tokenised deposits extend that idea to larger corporate flows in two currencies, including US dollars, which matter for trade.
If the service proves itself in this corridor, extending it to other ASEAN markets would be a natural step. The region's push to connect payment systems, including the Project Nexus initiative, creates a backdrop in which tokenised corporate liquidity could become part of regional infrastructure.
The choice of a two-currency service is also deliberate. Many regional companies hold US dollars for trade and Singapore dollars for operations, and moving both through the same tokenised rails simplifies treasury management. Adding Malaysian ringgit in future would be a logical step, subject to Bank Negara Malaysia's rules on foreign exchange.
What treasurers and banks should watch
For treasurers, the key questions are practical: which entities and currencies are supported, what the costs are compared with traditional transfers, how the service integrates with treasury management systems, and how auditors treat tokenised balances. Early adopters will shape the answers.
For other banks, OCBC's launch adds competitive pressure. DBS, UOB, Standard Chartered and HSBC are all active in tokenisation, and corporate clients will compare offerings. Ant International's expanding partnerships, including its work with HSBC on real-time treasury in the Middle East, show that non-bank platforms are positioning themselves as connectors between banks.
For regulators, production use of tokenised deposits raises questions about interoperability, operational resilience and supervision across borders. Singapore's MAS has supported tokenisation through its Project Guardian work, and Malaysia's central bank will watch how cross-border tokenised flows interact with its foreign exchange rules.
What did OCBC and Ant International launch?
A tokenised deposit solution for corporate treasury and liquidity transfers between Singapore and Malaysia, running on Ant International's WhaleRTP platform, launched in October 2026.
What is a tokenised deposit?
It is a digital representation of a commercial bank deposit recorded on a distributed ledger. Unlike a stablecoin, it remains a claim on the bank and sits inside the regulated banking system.
Which currencies does the OCBC service support?
The service moves Singapore dollar and US dollar liquidity across borders, including outside traditional banking hours.
How is a tokenised deposit different from a stablecoin?
A stablecoin is issued by a company backed by reserves, while a tokenised deposit is a bank liability subject to bank regulation. Treasurers often prefer tokenised deposits for safety and integration.
What is Ant International's Whale platform?
WhaleRTP, known as Whale, is Ant International's platform connecting blockchain-based assets from multiple financial institutions to support cross-border treasury and payments.
Has OCBC done other tokenisation projects?
Yes. OCBC launched a tokenised gold fund with Lion Global Investors in April 2026 and completed tokenised deposit transactions on Swift's ledger in September 2026.
The OCBC and Ant International launch is a modest announcement with a large implication. Tokenised deposits are now moving real corporate money between two of Southeast Asia's most connected economies, outside banking hours, inside the regulated system. For treasurers, that means fewer stranded balances and less reconciliation. For the wider market, it is evidence that banks intend to compete with stablecoins on speed while keeping the trust advantage of regulated deposits.
Talk to the SpinDepth deskYou've finished this story
Read on, send it to someone, or ask about it.