Vietnam has set one of the most ambitious financial inclusion targets in Southeast Asia. Its National Financial Inclusion Strategy for 2026 to 2030 aims for 95 percent of adults to hold transaction accounts, according to Vietnamese state coverage of the programme. That is not a slogan. The regulatory and infrastructure machinery to deliver it is already being installed.
Biometrics as the foundation
From January 2026, Vietnam made biometric identity verification mandatory for opening any new bank account or payment card. Banks must verify a customer's face either in person or through a trusted biometric database before activating any financial service. The State Bank of Vietnam's position is explicit: growth in digital banking must be anchored to higher-assurance identity verification rather than the frictionless onboarding funnels that were the competitive standard a few years ago.
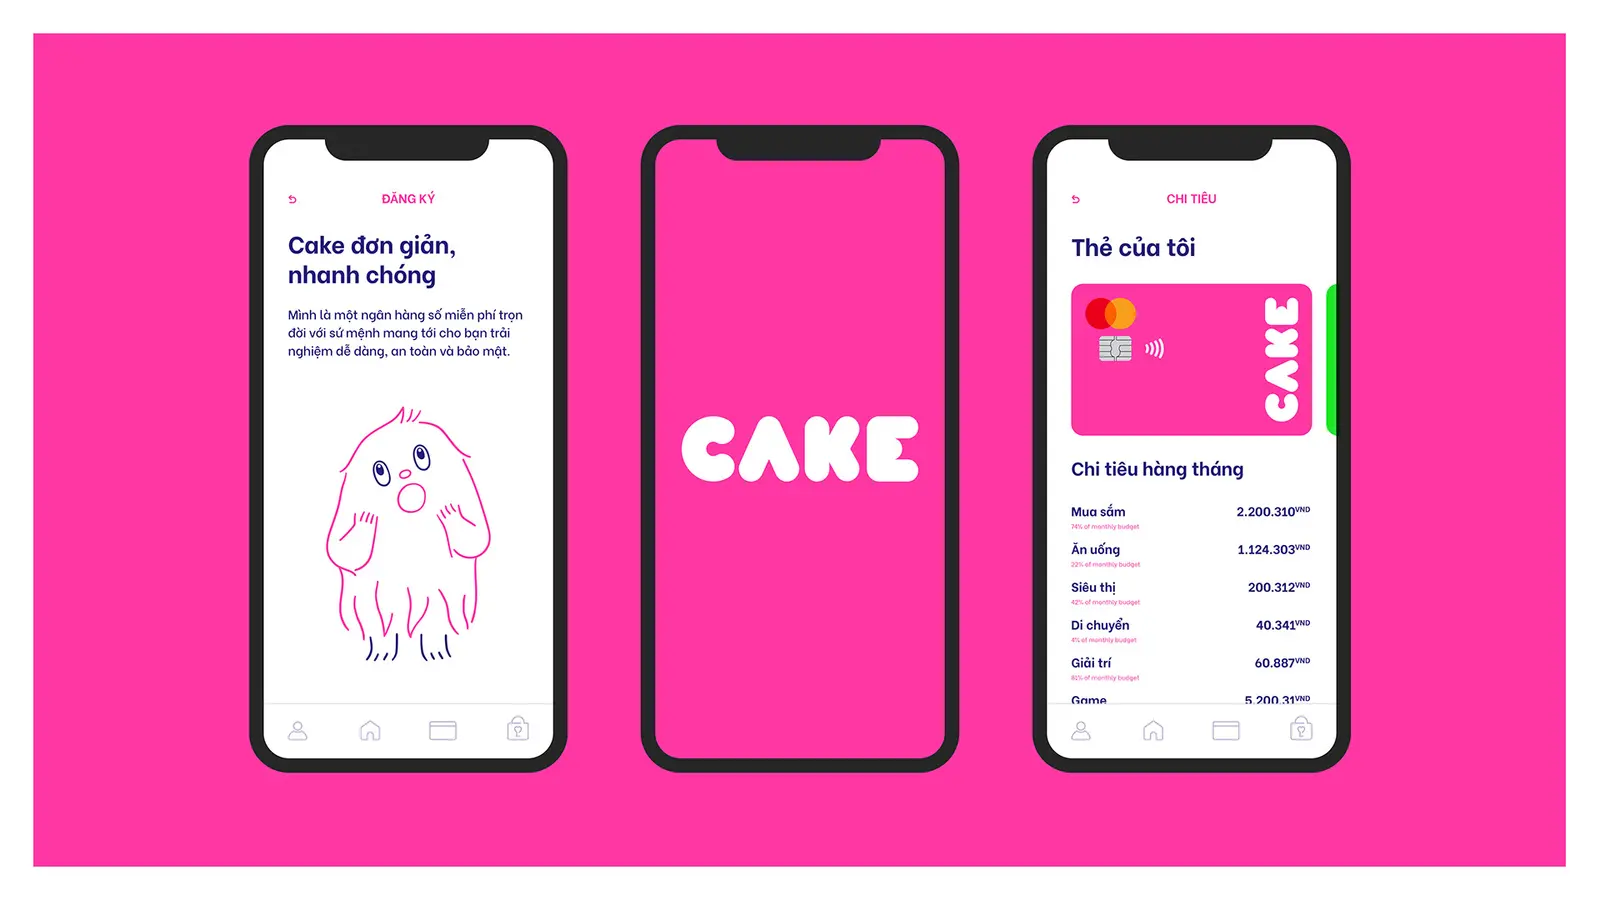
The market responded. Cake Digital Bank became the first in Southeast Asia to pass iBeta Level 2 testing for face biometric spoofing detection, deploying passive liveness detection across millions of users. In a market where verification standards are mandatory and testing benchmarks are public, investing in the strongest verification is not just compliance. It is a trust signal consumers can evaluate.
Payments that cross borders
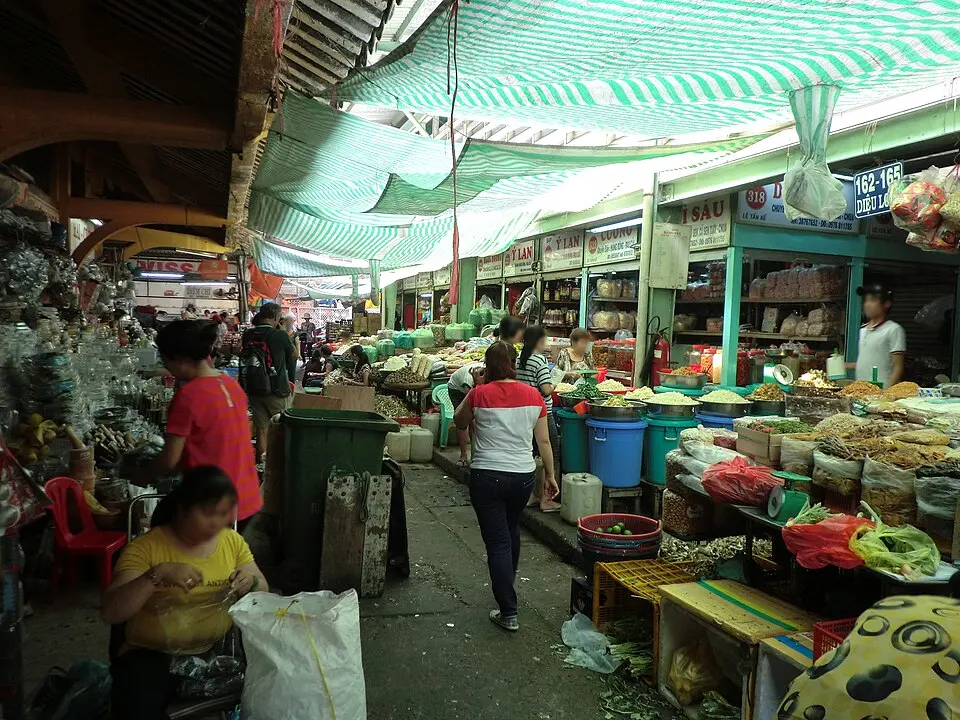
The second pillar is making digital money useful beyond Vietnam's borders. Cake by VPBank, backed by VPBank, launched a feature in 2026 letting Vietnamese users pay directly from their domestic dong accounts in Thailand, Laos and Cambodia through an interconnected cross-border network, with no foreign currency account and no cash required.
This sits inside a wider regional build-out. Thailand's PromptPay already connects through cross-border QR with Vietnam among others, according to Nation Thailand, and Project Nexus is standardising those connections across ASEAN.
Industry is mobilising
At Vietnam's Digital Finance Day 2026 in Ho Chi Minh City, banks including Vietcombank and VPBank showcased cross-border QR and single-QR merchant solutions, according to Vietnamese state media. Visa, a partner at the event, has been promoting QR-based cross-border transactions and contactless travel payments, according to Vietnam Investment Review.
Vietnam's fintech sector is also drawing capital and attention regionally. Indonesian and Vietnamese B2B payment infrastructure companies featured prominently in the Financial Times fastest-growing APAC fintech rankings, reflecting where regional investors see structural growth.
Vietnam is not choosing between growth and security. It is betting that mandatory high-assurance verification is what makes mass adoption safe enough to sustain.
What it means for foreign financial brands
The opportunity is large and the compliance baseline has risen. Any brand whose Vietnam entry plan was built around low-friction digital onboarding needs to redesign for mandatory biometric verification. Meanwhile the addressable market keeps expanding, both through the inclusion strategy and through Vietnam's broader capital market development.
The practical advice is to build verification quality into the product from the start, partner locally where distribution requires it, and communicate in Vietnamese with genuine local relevance. This is exactly where SpinDepth helps, building credible presence for financial brands entering Vietnam.
Where Vietnam is starting from
Vietnam has made rapid progress in bringing people into the banking system. Its previous national financial inclusion strategy aimed for at least 80 percent of adults to hold a bank account by 2025, and digital payments have grown quickly thanks to near-universal smartphone use and a national QR payment standard. Cash still matters, especially in rural areas and among older people, which is why the new target focuses on making accounts useful as well as widespread.
Why biometrics became the rule
Vietnam's banking system faced a wave of fraud using fake or borrowed identities, including accounts opened in other people's names and used to receive stolen money. The State Bank of Vietnam responded by requiring biometric checks. Since mid-2024, banks have had to verify customers' faces for larger online transfers, and the rules were then extended to account opening. Banks match a customer's face against chip-based national ID cards or the national population database, which makes it far harder to open accounts with false identities.
For customers, the change adds a step but reduces the risk of their identity being used by fraudsters. For banks and fintechs, it raises the cost and technical standard of onboarding.
How cross-border QR payments work
Cross-border QR payments link national payment systems so that a customer in one country can scan a merchant's QR code in another and pay from their home account. The payment is converted between currencies through the linked systems, often at better rates than card networks charge. Southeast Asian central banks have been linking their QR systems bilaterally for several years, and Vietnam is part of that network, with links to neighbours including Thailand, Cambodia and Laos.
For travellers and small businesses, these links make paying and getting paid across borders cheaper and simpler. For banks, they create new products and fee income.
What the target means for businesses
Reaching 95 percent of adults with transaction accounts would bring millions more people into digital payments, creating a larger market for lenders, insurers, investment platforms and merchants. It also means more first-time users of financial services, who need clear products, local-language support and protection from scams. Businesses that design for those users, rather than for the already banked, are best placed to benefit.
Risks along the way
Rapid digitisation brings risks: fraud schemes that target new users, data protection concerns around biometric data and the exclusion of people who struggle with digital tools. Vietnam has strengthened its rules on personal data protection, and banks are expected to invest in security and education. Progress towards the target will depend as much on trust as on technology.
Lessons for foreign financial brands
Foreign firms entering Vietnam need to plan for strict identity verification, local data rules and partnerships with licensed local institutions. Marketing must be in Vietnamese and relevant to local habits, such as QR payments and mobile banking apps. Firms that treat compliance as part of the product, rather than an obstacle, will find it easier to win both regulators' and customers' confidence.
What success would look like
If Vietnam reaches its target, the change will show up in everyday life: farmers receiving payments to their phones, small shops accepting QR payments from neighbouring countries, young workers building credit histories through digital accounts and families sending money home in seconds rather than days. Those outcomes, more than the headline percentage, are what the strategy is meant to deliver, and they are the measures worth watching over the coming years.
FAQs
Q1: What is Vietnam's financial inclusion target?
A1: 95 percent of adults holding transaction accounts, under the National Financial Inclusion Strategy for 2026 to 2030.
Q2: Is biometric verification mandatory in Vietnam?
A2: Yes. From January 2026, banks must verify a customer's face in person or via a trusted biometric database before activating any new account or card.
Q3: Can Vietnamese users pay abroad from local accounts?
A3: Cake by VPBank launched a feature allowing payment in Thailand, Laos and Cambodia directly from domestic dong accounts.
Q4: What should foreign fintechs prepare for?
A4: A higher verification compliance baseline, local partnership requirements, and Vietnamese-language product and communication.
For brands entering Vietnam, high-assurance verification is the entry ticket, and that is exactly where SpinDepth helps brands show up.
Source:
Source 1: Vietnam.vn, From international payments to cross-border money transfers
Source 2: Vietnam Investment Review, Visa backs Digital Finance Day 2026
Source 3: Nation Thailand, Thailand's Digital Payment Revolution
Source 4: Fintech News Singapore, Fastest-Growing Asia Pacific Fintechs 2026
You've finished this story
Read on, send it to someone, or ask about it.