How are Thailand's banks doing? Holding up, but under pressure. Kasikornbank and SCB X, two of the country's largest lenders, both reported lower third quarter profits, hit by bond market losses, lower fee income and the lingering effect of interest rate cuts. Kasikornbank's net profit fell 3.98 percent from the previous quarter to 12.72 billion baht, according to the bank's results statement, while SCB X's fell 4.0 percent to 10.68 billion baht, as reported by Kaohoon International.
The numbers matter beyond bank shareholders. Banks see the economy through millions of loans and deposits, and their results offer an early read on how Thai households and businesses are coping. KBank's chief executive described the recovery as K shaped: strong where the AI driven export cycle reaches, weak for households squeezed by living costs and debt.
What Kasikornbank reported
Kasikornbank's net profit attributable to shareholders was 12,720 million baht in the third quarter, a decrease of 527 million baht from the second quarter. The bank said this was partly due to lower non interest income related to financial instruments amid market volatility, and to a fall in net fee and service income of 550 million baht, or 5.29 percent, to 9,841 million baht, reflecting market conditions and the impact of new standardised fee regulations.
Net interest income was 31,602 million baht, broadly in line with the previous quarter, but it was down about 7.5 percent from a year earlier because of lower interest rates and rate cuts intended to ease customers' debt burdens. Over nine months, KBank's net profit rose 1,348 million baht to 40,635 million baht, showing that the first half was stronger.
Chief executive Kattiya Indaravijaya said the Thai economy in the third quarter was supported by government stimulus but that the recovery remained uneven. Activities linked to the AI cycle, especially electronics exports and digital investment, were key growth drivers, while tourism had yet to fully recover and households continued to face high living costs and elevated debt.
What SCB X reported
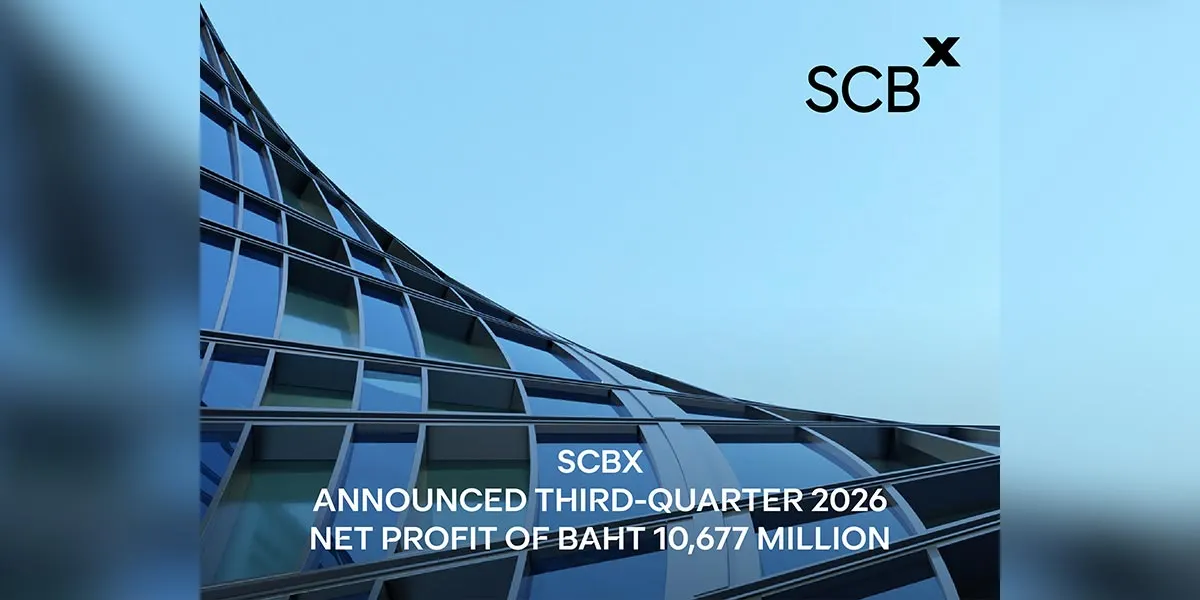
SCB X, the parent of Siam Commercial Bank, reported third quarter net profit of 10,677 million baht, down 4.0 percent from the previous quarter. The main drag was mark to market losses on debt securities as bond yields rose, while its core businesses remained resilient, according to Kaohoon International.
Its lending business held up. Net interest income rose 0.5 percent quarter on quarter to 27,452 million baht, and the net interest margin improved to 3.07 percent. Over nine months, however, SCB X's profit fell 14.3 percent to 31,989 million baht, reflecting a tougher year than KBank's.
Thai banks are not in trouble. They are mirroring an economy where AI exports boom and household budgets bust.
Analysts have been cautiously positive on SCB X. UBS upgraded the stock to buy in September and raised its target price to 165 baht, citing a discounted valuation, stronger 2027 earnings and possible capital returns, while flagging credit costs as the main risk.

Why bond losses hit Thai banks
The rise in global bond yields has been one of the defining market stories of 2026. US 10 year Treasury yields have approached 5 percent, and higher yields push down the value of bonds already held. Banks that hold government and corporate bonds in their investment portfolios must mark them to market, which creates losses on paper even if they never sell.
That is what weighed on SCB X and contributed to KBank's lower non interest income. It is a reminder that Thai banks are exposed not only to Thai borrowers but also to global financial markets, including the Federal Reserve's policy path and the oil driven inflation outlook.
Fee income faces its own pressure. KBank cited new standardised fee regulations, which limit what banks can charge for some services. Lower fees benefit consumers but reduce a profitable revenue line for lenders.
What it means for Thai households and the economy
The banks' commentary points to a divided economy. Exporters connected to the AI hardware boom are doing well, while households face high living costs and debt that limit spending. Tourism, a crucial driver of the Thai economy, has not fully recovered, and Prime Minister Anutin Charnvirakul said last week he expects growth to exceed 2.1 percent in 2026, citing foreign investment and exports that grew more than 20 percent, though that remains a modest pace.
For borrowers, the Bank of Thailand's low policy rate of 1 percent and banks' rate cuts have eased debt service costs, which is why net interest income has fallen from a year ago. The trade off is lower bank profitability, which can make lenders more cautious about extending new credit to riskier borrowers. The key indicators to watch include:
- Credit costs and non performing loans, especially in consumer and small business lending
- Net interest margins as rates stay low and competition for deposits continues
- Bond yields, which drive mark to market gains and losses
- Fee income under new standardised fee regulations
- Government stimulus and tourism recovery in the fourth quarter
We examined pressure on the baht in our report on the Thai baht's slide to a 15 month low, which affects banks through trade finance and foreign currency lending.
The outlook for Thai banks
The fourth quarter will test whether the slowdown in profits is temporary. If bond yields stabilise, mark to market losses could reverse, lifting SCB X's earnings. If government stimulus supports consumption and tourism improves, loan demand and fee income could recover. KBank expects continued government measures to stimulate consumption to provide some support in the final quarter.
The risks remain household debt and the global environment. A sharper slowdown or a spike in loan defaults would hit both banks' profits more seriously than the modest declines seen so far. For now, Thailand's largest banks are profitable, well capitalised and cautious, reflecting an economy that is growing but unevenly.

How much did Kasikornbank earn in Q3 2026?
Kasikornbank reported net profit attributable to shareholders of 12,720 million baht, down 3.98 percent from the second quarter.
Why did KBank's profit fall?
KBank cited lower non interest income from financial instruments amid market volatility and a 5.29 percent drop in net fee income, partly due to new standardised fee regulations.
How much did SCB X earn in Q3 2026?
SCB X reported net profit of 10,677 million baht, down 4.0 percent from the previous quarter.
Why did SCB X's profit fall?
The main drag was mark to market losses on debt securities as bond yields rose.
What is SCB X's net interest margin?
SCB X's net interest margin improved to 3.07 percent in the third quarter.
How did the banks do over nine months?
KBank's nine month profit rose 1,348 million baht to 40,635 million baht, while SCB X's fell 14.3 percent to 31,989 million baht.
What is a K shaped recovery?
It describes an economy where some sectors, such as AI linked exports, grow strongly while others, such as household consumption, remain weak.
Who is Kasikornbank's chief executive?
Kattiya Indaravijaya is Kasikornbank's chief executive officer.
Why do rising bond yields hurt banks?
Higher yields reduce the value of bonds banks already hold, creating mark to market losses in their investment portfolios.
What is the Bank of Thailand's policy rate?
The Bank of Thailand's policy rate is 1 percent.
Are Thai banks at risk?
Both banks remain profitable and well capitalised, but household debt and credit costs are the main risks to watch.
What did UBS say about SCB X?
UBS upgraded SCB X to buy in September 2026 with a 165 baht target, citing valuation, stronger 2027 earnings and possible capital returns.
How fast will Thailand's economy grow in 2026?
Prime Minister Anutin Charnvirakul said he expects growth to exceed 2.1 percent in 2026.
What are standardised fee regulations?
They are new rules that standardise and limit certain fees Thai banks can charge customers. KBank said they contributed to a 5.29 percent fall in its net fee income.
Are Thai bank profits rising or falling this year?
It depends on the bank. KBank's nine month profit rose 1,348 million baht to 40,635 million baht, while SCB X's nine month profit fell 14.3 percent to 31,989 million baht.
What did KBank say about the fourth quarter?
KBank said continued government measures to stimulate consumption are expected to provide some support in the final quarter, though the recovery remains uneven.
What is SCB X?
SCB X is the parent company of Siam Commercial Bank and a group of financial technology businesses in Thailand.
Kasikornbank and SCB X's third quarter results show Thai banks steady but squeezed, caught between low interest rates, rising bond yields and tighter fee rules. Their commentary confirms an economy split between booming AI exports and struggling households. For investors and borrowers alike, the fourth quarter will reveal whether stimulus and tourism can narrow that divide.
Talk to the SpinDepth deskYou've finished this story
Read on, send it to someone, or ask about it.