For the price of a sweet at a roadside stall, Indonesians can now insure themselves against a rainy day, literally. Singapore-headquartered insurtech Igloo and DANA, one of Indonesia's largest digital wallets, have launched DANA Rain Protection, a parametric weather product that costs Rp500 per policy. If rainfall at the user's location reaches 2.5 millimetres or more during the coverage period, compensation is paid automatically. There are no claim forms, no documents and no officer visit. The claim is validated with satellite rainfall data and the GPS coordinates of the user.
The companies describe it as the first all-in-one rain protection product for everyday consumers in Indonesia. Whether or not that claim holds in every detail, the design is notable. It takes a type of cover that has mostly served farmers and large businesses and packages it as a micro-purchase inside an app that millions of people already open to pay for transport, food and bills.

How parametric rain cover actually works
Traditional insurance pays for a loss after someone proves the loss happened. A damaged phone is inspected, a hospital bill is submitted, an assessor visits a flooded shop. Parametric insurance flips that logic. The policy pays when an agreed, measurable event occurs, whatever the individual loss turns out to be. In this case, the event is rainfall of at least 2.5 mm at the insured person's location, measured by satellite data rather than by a claims handler.
That design removes most of the cost that makes small policies uneconomic. There is no assessment, no paperwork to process and no dispute about how much was lost. The payout is triggered by data that the insurer and the customer can both see. For a policy priced at Rp500, those savings are the difference between a product that can exist and one that cannot.
The trade-off is basis risk. A user can be soaked and still not receive a payout if the measured rainfall stays under the threshold, or receive a payout on a day when the rain caused them no real problem. Parametric products work when customers understand that they are buying protection against an event, not reimbursement for a specific loss. Clear in-app explanations of the trigger are what keep that trade-off from turning into complaints.
Who the product is built for
The release lists the everyday disruptions the cover is designed around: higher online transport fares when it rains, cancelled outdoor plans, travel delays, and fewer customers for small businesses that depend on foot traffic. Anyone who has tried to book a ride in Jakarta during a downpour will recognise the problem. Prices jump at exactly the moment people need transport most.
Igloo co-founder and CEO Raunak Mehta said parametric insurance has long helped farmers and that the technology now makes similar protection accessible to the general public, including people who have to keep working in heavy rain. DANA chief finance officer Yattha Saputra said unpredictable weather affects mobility, daily activity and income, and that the product offers affordable cover inside payment flows users already know, with automatic payouts and no waiting period.
That positioning matters for distribution. Rain cover sold as a separate insurance product would struggle for attention. Rain cover offered at the moment someone is already paying for a ride or a delivery inside DANA reaches people when the risk is on their mind, which is the core idea behind embedded insurance.
- Price: Rp500 per policy for DANA Rain Protection.
- Trigger: rainfall of 2.5 mm or more at the user's location during the cover period.
- Claims: automatic, validated with satellite rainfall data and GPS, no documents.
- Companion launch: DANA BNPL Protection at Rp1,000 a month.
In a market with insurance penetration near 2.7 percent, the first policy most people buy may be a Rp500 rain cover that pays without a form.
The BNPL cover launched alongside it
DANA also introduced DANA BNPL Protection, priced at Rp1,000 per month. It covers the outstanding buy now, pay later balance, including interest and penalties, if the user dies, suffers permanent disability, is hospitalised after an accident for two days or more, or loses their job. It sits next to a list of earlier Igloo and DANA products that includes electronics protection, phone screen cover, food poisoning protection, movie ticket cancellation and cyber protection.
Credit protection attached to BNPL is a sensible pairing. Indonesia's BNPL market has grown quickly, and so have concerns about consumers taking on repayments they cannot sustain after a shock to their income. A small monthly premium that clears the balance in defined hardship events protects the borrower, the lender and the platform's reputation at the same time.
For regulators, products like this are a useful test case. They show whether embedded insurance can be sold in a way that is clear about what is covered, priced fairly, and paid quickly when the trigger is met. Those are the questions that will decide whether micro-insurance in wallets is treated as consumer protection or as an add-on that needs closer scrutiny.
Why Indonesia is the market to watch
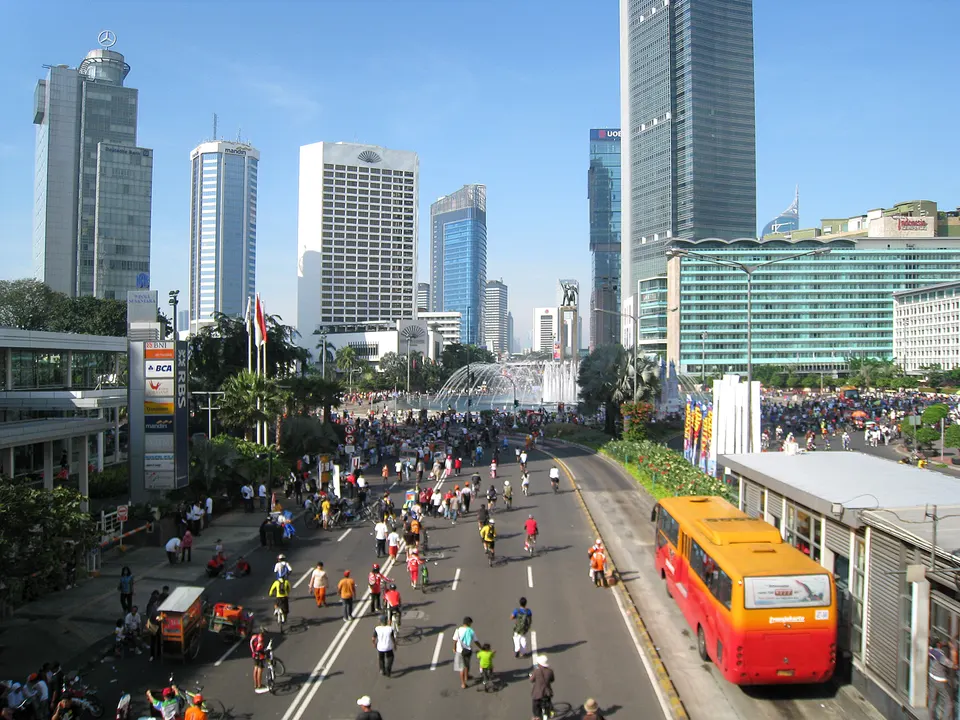
Indonesia has around 280 million people, and the release puts insurance penetration at about 2.7 percent, among the lowest in the region. That combination makes it one of the largest protection gaps in the world. Closing even part of it requires products that are cheap, simple and sold through channels people already use, which in Indonesia increasingly means e-wallets, super-apps and telcos.
Igloo has been building exactly that kind of distribution. The company works with more than 100 partners across six markets, according to figures reported in June, and its Indonesian partnerships include Telkomsel for digital distribution. In January, Tokio Marine took a 1.65 percent stake in Igloo for 5 million US dollars, a sign that established insurers see value in the distribution technology that insurtechs have built. Regulators elsewhere in the region are opening the door to fully digital insurers too, as our report on Malaysia's digital insurer licence window showed.
The same rain-trigger technology could be offered to ride-hailing and delivery platforms, restaurants, retailers, event organisers and tourism businesses, according to Igloo. Each of those is a business whose revenue falls when it rains, and each has a customer base that can be reached through a digital channel. If the consumer product proves popular, the commercial versions are a natural next step.
The lesson for platforms and insurers
For wallets and super-apps, the lesson is that insurance can be a feature rather than a separate product line. A rain cover offered at checkout adds a sliver of revenue per transaction, but more importantly it gives users a reason to keep their balance and their habits inside one app. Every automatic payout is also a moment of goodwill that a platform can point to when it competes for attention with rivals.
For insurers, the lesson is about who owns the customer. Underwriters bring capital and licences, but the relationship increasingly sits with the platform where the customer spends time. Insurtechs such as Igloo position themselves in the middle, providing the product design, pricing engines and claims automation that let a traditional insurer reach customers it could never serve through agents.
That middle position is valuable only while it stays efficient. If the cost of servicing a Rp500 policy creeps upward, or payouts are disputed, the economics break quickly. The companies that win embedded insurance in Southeast Asia will be the ones that keep claims fully automatic and explain triggers in plain language, which is exactly what this launch is testing at scale.
What could hold it back
Weather data quality is the first constraint. Parametric products are only as trustworthy as the measurements behind them, and satellite rainfall estimates at street level carry uncertainty. Customers who feel the data got it wrong on a stormy day will judge the product harshly, which makes transparent trigger reporting inside the app essential.
The second constraint is understanding. Many first-time insurance buyers in Indonesia have never held a policy, and some associate insurance with slow claims and fine print. A Rp500 product that pays automatically can change that perception, but only if users clearly see the payout arrive. The marketing challenge is less about price and more about proof.
The third is economics. Micro-premiums only add up with very large volumes and very low servicing costs. Igloo's broader push, which we cover separately in our look at insurtech's shift toward parametric and embedded distribution, depends on automation keeping each policy's cost close to zero.
What is DANA Rain Protection?
It is a parametric weather insurance product built by Igloo and sold inside the DANA e-wallet in Indonesia. It costs Rp500 per policy and pays automatically when rainfall at the user's location reaches 2.5 mm or more during the coverage period.
How do I claim DANA Rain Protection?
You do not file a claim. The payout is validated automatically using satellite rainfall data and your GPS location, with no documents or officer verification required.
Who is Igloo?
Igloo is a Singapore-headquartered insurtech founded in 2016 as Axinan. It builds digital insurance infrastructure and embedded insurance products with partners such as e-wallets, marketplaces, telcos and banks across Southeast Asia.
What is parametric insurance?
Parametric insurance pays a pre-agreed amount when a measurable event happens, such as rainfall above a threshold, instead of reimbursing a loss that has to be assessed. It is faster and cheaper to run, but payouts may not match each person's actual loss.
What else did DANA launch with Igloo?
DANA BNPL Protection, priced at Rp1,000 per month, which covers an outstanding buy now, pay later balance in cases of death, permanent disability, accidental hospitalisation of two days or more, or job loss.
DANA Rain Protection is a small product with a large signal. It shows that parametric insurance, long reserved for crops and corporate risk, can be priced and distributed like a digital good in one of the world's least insured large markets. If Igloo and DANA can prove that payouts arrive reliably and users understand the trigger, rain cover could become the first insurance policy millions of Indonesians ever buy, and the template for weather protection across Southeast Asia's super-apps.
Talk to the SpinDepth deskYou've finished this story
Read on, send it to someone, or ask about it.