Colombia's fintech story has been a rare bright spot in Latin American finance, but Global Finance Magazine reports the boom has reached its first real policy test. After years of rapid adoption and startup formation, the sector now faces regulatory and macro decisions that will decide whether Colombia builds a durable digital finance market or simply a crowded one. The moment is familiar to anyone watching emerging markets from Jakarta to Lagos: the easy growth phase ends, and the rules phase begins.
Why Colombia moved fast
Colombia combined a large unbanked population, high mobile penetration, and a relatively open regulatory stance toward innovation sandboxes. That mix pulled in consumer lenders, payments startups, and neobanks chasing a young, underserved population. Firms like Rappi, the delivery super-app that expanded into financial services, became symbols of a region where the phone became the bank branch. The growth was real, but it was also shallow where identity, credit bureaus, and consumer protection lagged.
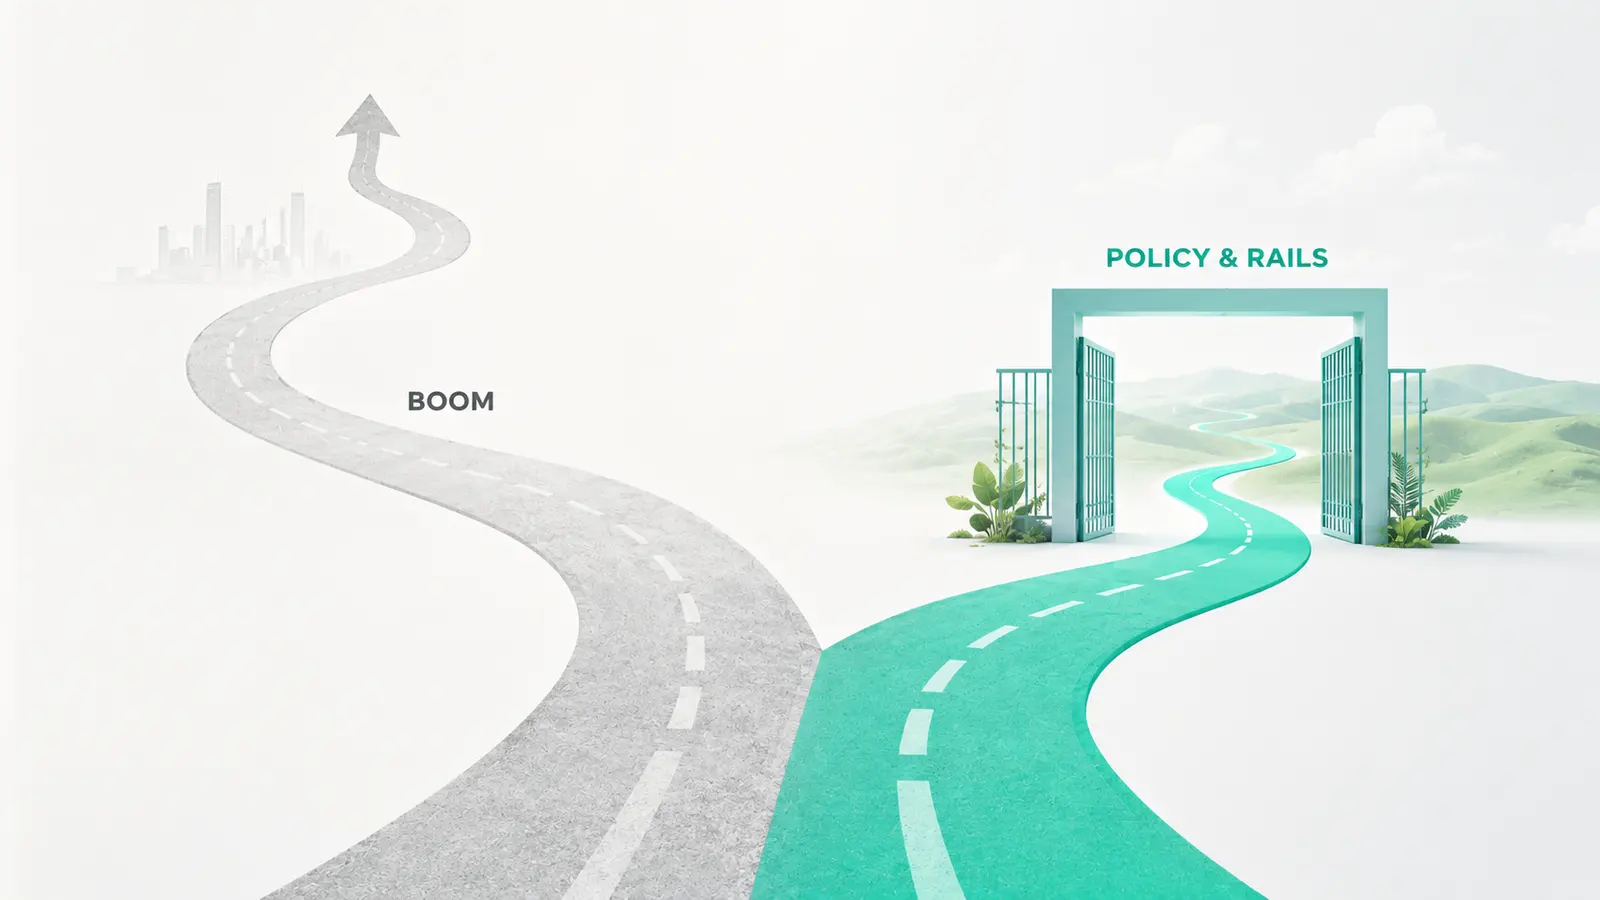
The policy test is therefore about depth, not pace. Can the state build the rails, digital identity, credit infrastructure, and borrower safeguards, that turn first-time users into a stable financial class? Without them, a fintech boom can invert into a bad-debt and fraud cycle that invites a regulatory clampdown, the classic emerging-market trap.
- Large unbanked base plus high mobile penetration
- Open stance on innovation sandboxes pulled in startups
- Growth was real but shallow on identity and credit rails
- The test now is market depth, not user pace
The APAC parallel
Colombia's crossroads is a mirror for Southeast Asia. Markets like Indonesia and the Philippines rode the same unbanked-plus-mobile wave, and they now face the same depth questions: does the regulator build inclusive rails fast enough to keep the boom from curdling? The firms that thrived in both regions share a trait: they treated regulatory building as a partner exercise, not an obstacle to route around. Our [APAC Briefing desk](Robinhood Just Let AI Agents Take the Wheel on Retail Portfolios) tracks these inflection points as the moments that separate a ten-year franchise from a two-year spike.
Policy risk as market risk
For investors and operators, Colombia is a reminder that in emerging markets the binding constraint is rarely demand. It is the rule set that determines whether demand becomes revenue or write-offs. A fintech that models only adoption and ignores the policy cycle is modelling half the business. The Colombia test is a live case study in pricing that other half.
The easy growth phase ends, and the rules phase begins.
The building blocks Colombia has put in place
Colombia's financial authorities have taken several steps to support digital finance. The Financial Superintendence, which supervises banks and financial firms, has run a regulatory sandbox that lets new firms test products under supervision. The government has issued rules on open finance, setting a framework for customers to share their financial data with authorised third parties. And the central bank, Banco de la República, has built Bre-B, an instant payment system designed to let people and businesses send money between institutions in seconds using simple keys such as phone numbers.
These pieces address the depth problem: identity, data sharing and payments that work across institutions rather than inside individual apps.
Mobile wallets and the unbanked
Mobile wallets such as Nequi, owned by Bancolombia, and Daviplata, linked to Banco Davivienda, brought millions of Colombians into digital payments, helped by government transfer programmes paid through them. Digital banks and foreign entrants, including large Latin American neobanks, have added competition. The challenge now is to move users from basic payments to savings, credit and insurance that improve their financial lives.
Credit, interest caps and responsible lending
Colombia sets a legal maximum interest rate, the usury rate, which the Financial Superintendence updates regularly. The cap protects borrowers but also limits how much lenders can charge riskier customers, which shapes which fintech lending models can work. Responsible lending also depends on good credit data: when new borrowers have little history, lenders rely on alternative data, and the risk of over-indebtedness rises if several apps lend to the same person without sharing information.
The parallels with Southeast Asia
Indonesia and the Philippines followed similar paths: rapid growth in e-wallets and digital lending, followed by regulators tightening rules on lending apps, data use and collection practices. Indonesia's financial regulator cracked down on illegal lending apps and set rules for licensed peer-to-peer lenders. The lesson in each case is that early growth on payments must be followed by investment in credit infrastructure and consumer protection, or problems with bad debts and abusive practices can damage trust in the whole sector.
What investors look for now
Investors in emerging-market fintech increasingly look for businesses with clear routes to profitability, strong risk management and good relationships with regulators. A large user base is no longer enough. Firms that can show healthy loan performance through an economic cycle, low costs to serve customers and compliance with tightening rules attract capital more easily than those growing users at any cost.
A checklist for operators entering Colombia
- Understand the licensing route: sandbox, partnership with a licensed entity or a full licence.
- Plan for the usury rate cap in lending products.
- Prepare to connect to Bre-B and open finance frameworks.
- Invest in credit data and collection practices that meet consumer protection standards.
- Build relationships with regulators early.
What this means for operators
Operators in emerging markets should watch Colombia the way they watch their own regulators: as a preview. Build for the rails that are coming, digital identity, shared credit infrastructure, transparent pricing, because the firms that align with the eventual rule set capture the users the clampdowns shake loose. Those that optimize purely for the pre-rule window get flattened when it closes.
The Colombia moment is not a warning against emerging-market fintech. It is a cue to respect the second half of the cycle. Booms are won on product. Markets are won on policy alignment. The countries and companies that internalize both will still be standing when the test results come back.
Is Colombia's fintech boom in danger of collapsing?
Not necessarily. The risk is a shallow boom curdling into bad debt or a clampdown if identity and consumer-protection rails are not built. The outcome depends on policy, not demand.
Why should APAC operators care about Colombia?
It is a live mirror of the same unbanked-plus-mobile trajectory and the same regulatory crossroads Southeast Asia is navigating.
What is Bre-B?
Colombia's instant payment system, built by the central bank, which lets people and businesses send money between institutions in seconds.
What is the usury rate in Colombia?
The legal maximum interest rate, updated regularly by the Financial Superintendence, which caps what lenders can charge.
Why do fintech booms face policy tests?
Because growth in payments must be followed by credit infrastructure, data sharing and consumer protection for the market to become stable.
Colombia's fintech boom was the easy part. The policy test is the real one, and it will be repeated, with local accents, across every emerging market that bet on financial inclusion through the phone. The operators who read the test as the product, not the fine print, will be the ones still growing when the rules settle.
Speak with the SpinDepth deskYou've finished this story
Read on, send it to someone, or ask about it.